
See what your home loan rate is really costing you.
Put in your numbers and see the difference a lower rate makes. Then Tom compares our panel of 75 lenders, including green and ethical options, and tells you honestly whether switching is worth it. Move to an eligible green lender and we cover the standard costs of switching.
- No fees for our service, ever
- Switching costs covered when you move to an eligible green lender
- Honest guidance, even if you shouldn't move
Eligible home loan refinances from a non-green lender. Conditions apply. See how the offer works.
Repayment check
Principal & interestIllustrative only. Excludes fees, charges and switching costs. If you move to an eligible green lender, we may cover the standard switching costs. Your result depends on your loan, lender eligibility and credit criteria.
Refinancing in Sydney and All Over Australia
Most people overpay their lender for years without realising it.
Banks rely on inertia. Most borrowers set up their loan and never review it, which means they gradually drift onto higher rates as new customers get better deals. By the time you notice, you may have been overpaying for years.
Refinancing isn't just about chasing a lower number. It can mean restructuring your loan to pay it off faster, unlocking equity for renovations or investment, consolidating debt into a more manageable position, or moving to a lender whose values line up with yours, without giving up a competitive rate.
We review your current loan, run the numbers honestly, and tell you whether moving makes financial sense. If it doesn't, we'll say so.
We're based in Sydney, but our lender panel and process work exactly the same wherever your property is: Melbourne, Brisbane, Perth, regional NSW, anywhere in Australia. Most of our work happens by phone, video call and email, so your postcode never limits your options.
Why People Refinance
There are more reasons to refinance than most people consider.
Rate is the obvious one. But it's rarely the only one worth looking at.
Lower Your Rate
If you haven't reviewed your rate in the last two years, there's a strong chance a better deal exists. We find it and negotiate it on your behalf.
Reduce Monthly Repayments
A lower rate or extended loan term can meaningfully reduce what you pay each month, freeing up cash flow for other priorities.
Access Your Equity
If your property has grown in value, you may be able to refinance and unlock equity for renovations, an investment deposit, or other goals.
Consolidate Debt
Rolling higher-interest debt into your home loan can simplify your finances and significantly reduce your overall interest burden.
Pay Off Faster
Switching to a loan with better offset or redraw features can cut years off your mortgage without increasing your repayments.
Move to a Green Lender
Some of the sharpest rates right now come from lenders that won't fund fossil fuels, so you don't have to choose between price and principle.
Refinancing to a Green or Ethical Lender
Prefer a lender that doesn't fund fossil fuels? You usually don't have to pay more for it.
Customer-owned banks and green lenders are currently pricing some of the sharpest variable rates on the market, and several offer an extra discount if your home meets basic energy-efficiency standards. They don't finance coal, oil and gas projects, live animal exports, or nuclear weapons, and many are certified B Corps or member-owned mutuals. We compare them against your current loan and the rest of our panel, and tell you honestly whether switching stacks up, on price and on principle.
Stop Funding Fossil Fuels
Green lenders have public policies ruling out coal, oil and gas financing, so your repayments won't go toward it either.
Often a Sharper Rate
Green and mutual lenders are pricing some of the lowest variable rates in the country right now, not just the "feel-good" option.
A Discount for an Efficient Home
Solar, insulation, double glazing, or a 7-star NatHERS rating can unlock an additional discount most standard lenders don't offer.
Green Lender Switch Offer
Move to a green lender and we'll cover the cost of switching.
Switching lenders comes with fees, and those costs are often what keeps people with a lender that keeps lifting their rate. If you refinance your home loan from a lender that isn't a green lender to one of the green lenders on our panel, Echidna Equity covers the standard costs of moving your loan.
What we cover
- Your current lender's discharge fee
- The new lender's application, establishment, valuation and settlement fees
- Government fees to discharge your old mortgage and register the new one
What we don't cover
- Fixed rate break costs
- Lenders mortgage insurance and stamp duty
- Legal, conveyancing or accounting fees you choose to engage
- Arrears, penalty interest, or ongoing fees and interest on either loan
Who it's for
- Owner-occupied and investment home loan refinances
- Your current lender is not a green lender
- The new loan settles through Echidna Equity
- Once per client
How it works. Before you apply, we confirm in writing which costs we'll cover and the maximum amount. You pay the costs at settlement as usual, and we reimburse them to your nominated account within 60 days of settlement, once we have your settlement statement or invoices.
Guidance comes first. We only recommend a green lender if it genuinely suits your needs and objectives. The offer is never the reason we recommend a lender, and you're free to decline it.
Good to know. A green lender is one on our panel with a public policy of not financing fossil fuel projects, and we confirm a lender qualifies before you apply. The offer doesn't apply to moves from one green lender to another, or to repricing with your current lender. You agree to keep the loan for at least two years. When we cover your costs, we don't make the per-loan AWC donation for that loan, but our annual donation of 1% of profits continues as normal.
Our Review Process
We look at the full picture, not just the rate.
A rate comparison tells you one number. We run a proper review that factors in everything that affects whether refinancing actually saves you money, and whether a green lender is genuinely a fit.
Current Rate vs Market
We benchmark your existing rate against what's available today across 75 lenders, including deals that aren't advertised publicly.
Break Costs and Exit Fees
Some fixed loans carry exit costs that wipe out any savings from moving. We calculate these upfront so there are no surprises.
Loan Features and Structure
Rate is one variable. Offset accounts, redraw facilities, and repayment flexibility can be worth more than a slightly lower headline rate.
Your Equity Position
We check your current loan-to-value ratio to confirm whether you qualify for more competitive rates and identify any equity available to you.
True Cost of Switching
We model the net saving after accounting for application fees, valuation costs, and the time it takes to break even on the switch. If you're moving to an eligible green lender, we cover the standard switching costs, which shortens that break-even point.
Your Current Lender's Retention Rate
Sometimes your existing lender will match a better rate rather than lose you. We use competing offers to negotiate on your behalf before you move.
Your Home's Green Eligibility
Most green loan discounts require a 7-star NatHERS rating, solar, or verified efficiency upgrades. We check what your property qualifies for before you apply.
A Lender's Fossil Fuel Policy
We check each green lender's public responsible-lending policy, so you know exactly what you're switching to, not just what it costs.
How a switch works with us
A switch usually takes about a month. If your documents are in order, it can be as quick as two weeks.
- STEP 130-minute chatSend your latest statement and tell us what you want from the loan.
- STEP 2
 Tom compares the panelRates, fees and switching costs across 75 lenders, shown side by side.
- STEP 3You decideIf staying put is best, we'll say so. If switching wins, you choose the lender and structure. For an eligible green switch, we confirm in writing which costs we'll cover before you apply.
- STEP 4
 Lorenzo runs the switchPaperwork, lender follow-up and settlement, with updates at every stage.
Client Stories
When the numbers finally made sense.
A good refinance isn't just a lower rate. It's a better loan structure, and sometimes a better lender, working harder for you over the long term.
John and Sandra: From Stuck to Scaling
John and Sandra came to us with a $1.6 million loan and two problems most lenders wouldn't touch. Sandra had just started a new job, and John's income was commission-based. Every bank they approached directly hit a wall. We found a lender that assessed their full financial position rather than just their employment history, refinanced the loan at a significantly better rate, and saved them over $250,000. They used the freed-up equity to purchase their third investment property within twelve months.
Priya and Daniel: Same Home, Different Bank
Priya and Daniel had a $750,000 loan with a major bank, on a rate they'd never questioned. After adding solar panels the year before, we found their home now qualified for a customer-owned lender's Clean Energy Home Loan, priced comfortably below their existing rate once the efficiency discount was applied. The switch cut roughly $4,000 a year in interest, and moved their mortgage to a bank with a public policy against fossil fuel financing. They didn't have to choose between the two.
The Team
You'll always know who's working on your refinance.
We keep our client load manageable by design. Every file, general refinance or green lender switch, is handled by Tom, our broker, and managed day to day by Lorenzo, not passed to a junior processor or lost in a queue.

Lorenzo Suarez
Lorenzo is your main point of contact from first call to settlement. He keeps your paperwork moving, follows up the lender and makes sure you always know what happens next.
Clients regularly mention how quickly he replies, even after hours.
Cert IV Finance & Mortgage Broking
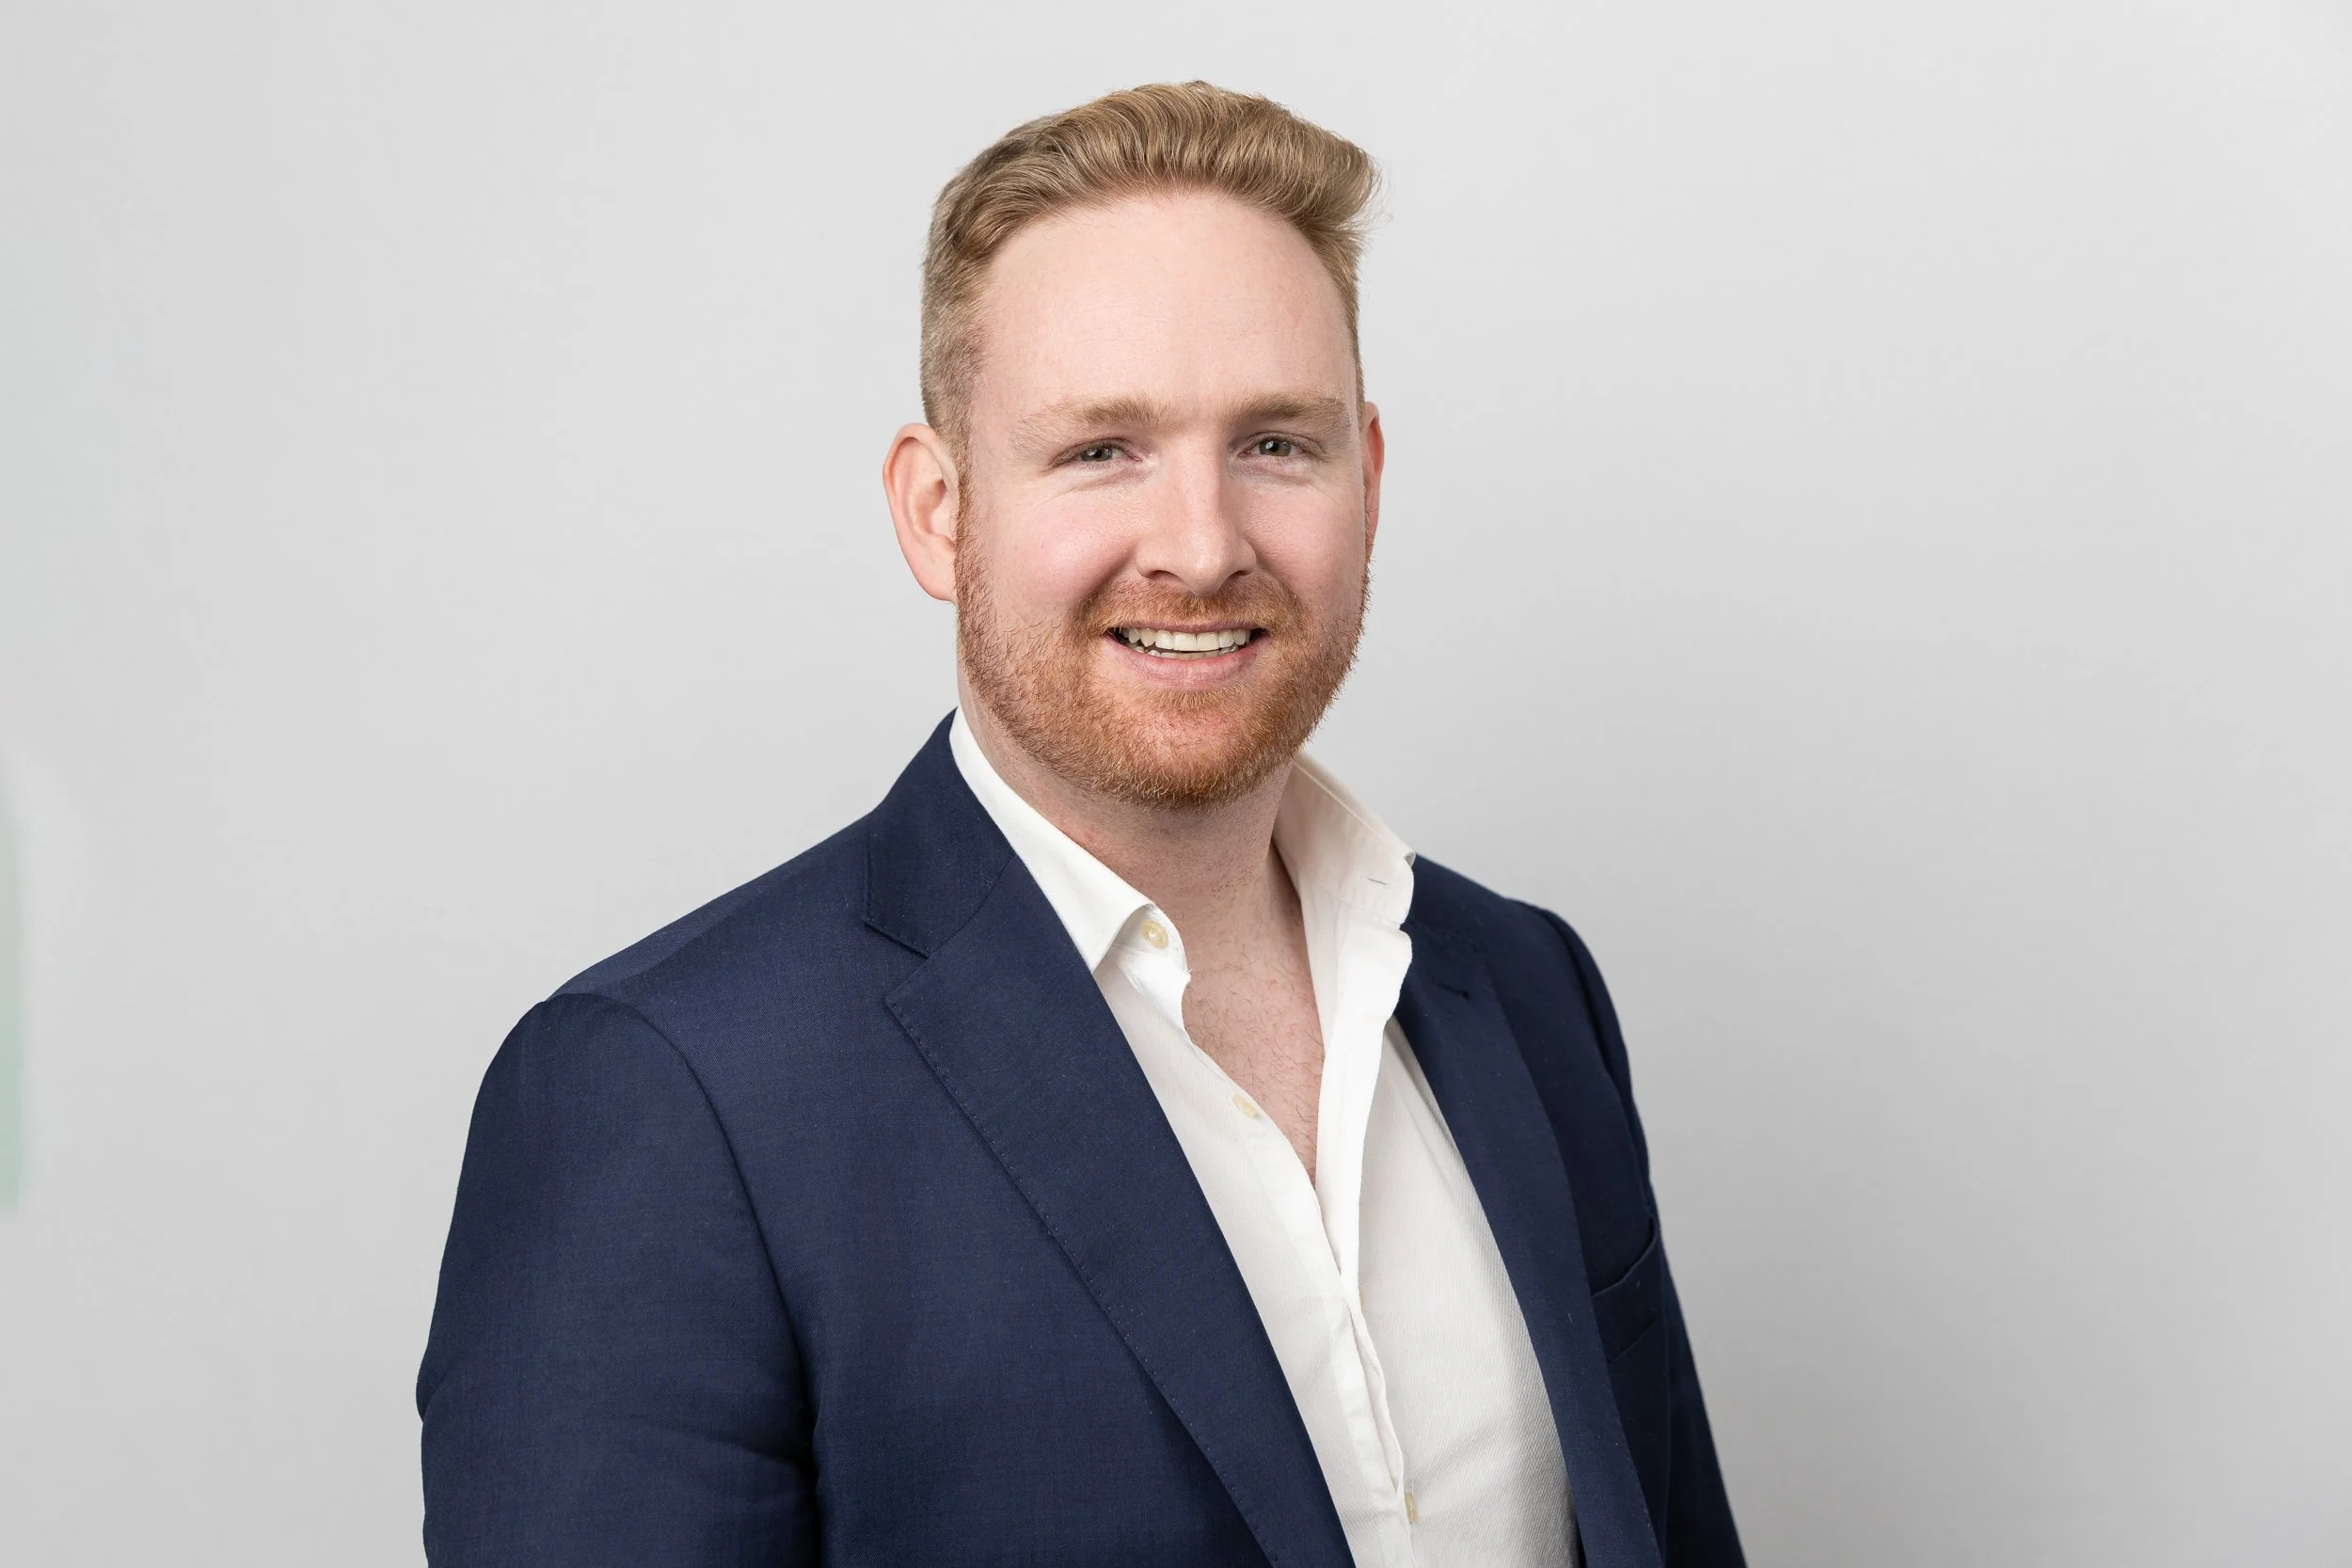
Tom Williams
Tom co-founded Echidna Equity with a clear brief: personal service, genuine lender access, and a business that gives back. As our mortgage broker, Tom assesses every application and recommends the lender and loan structure that suit you.
When he says the job is not done until clients start defying gravity, he means it literally.
Cert IV Finance & Mortgage Broking
Why This Matters To Us Too
We put a portion of our own profit behind conservation, not just our clients' loans.
Green refinancing isn't just about interest rates for us. It's a natural extension of something we already do: a portion of Echidna Equity's profit goes to the Australian Wildlife Conservancy, which protects native species and manages land across the country.
We don't think a mortgage broker can solve climate change. But we can make sure the guidance we give doesn't ignore it, and that some of what we earn goes toward looking after the country our clients call home.
A share of our profits is donated to the Australian Wildlife Conservancy, supporting the protection of native species and habitat across Australia.
It's a small, ongoing commitment built into how we do business, the same one we made long before you found this page.
Common Questions
What people ask us before refinancing.
Refinancing involves more moving parts than most people expect. Here are the questions we hear most often.
Get in Touch
Speak to a broker today.
Fill in the form and Lorenzo or Tom will be in touch within one business day. No obligation, no sales pitch, just a straight answer on what's possible for your loan, standard or green.
Book a refinance review
We'll get back to you within one business day.
By submitting this form you consent to Echidna Equity contacting you regarding your enquiry. We do not share your details with third parties. General information only. This does not constitute financial advice.
Message received.
Lorenzo or Tom will be in touch within one business day.
Find out what your loan should be costing you, and who it could be with.
A review takes fifteen minutes. We'll tell you exactly whether switching makes sense, rate and lender, wherever in Australia you're based.
Echidna Equity Pty Ltd ACN 678 592 713. Credit Representative Number 562940 of Australian Credit Licence 384704. Suite 302, 13/15 Wentworth Ave, Sydney NSW 2000. Echidna Equity is based in Sydney and provides mortgage broking services to clients all over Australia. General information only. This does not constitute financial, tax or legal advice and does not take into account your objectives, financial situation or needs. Credit criteria, terms and conditions apply. Interest rates, fees, product features and lender eligibility criteria for green or discounted loans vary by lender and change over time without notice; any rate, discount or saving referenced on this page is general and indicative only, and should be confirmed directly with us for your circumstances. Break costs vary by lender and loan contract. Client stories on this page are illustrative composites, not identifiable individuals. The green lender switch offer applies only to eligible residential home loan refinances from a lender that is not a green lender to a green lender on our panel, settled through Echidna Equity. Covered costs and the maximum amount are confirmed in writing before you apply. Break costs, lenders mortgage insurance, stamp duty and your own legal fees are not covered. A two-year loan commitment applies. Full terms at echidnaequity.com/terms-and-conditions.