
Grow the business.
Keep the cash flow.
Echidna Equity arranges equipment, vehicle and asset finance for businesses, sole traders and new ABN holders, so the gear gets working now and is paid for as it earns. Any fee is disclosed upfront.
Equipment Finance in Sydney and All Over Australia
The right structure matters as much as the rate.
Utes, trucks, excavators, medical and dental equipment, commercial kitchens, IT and office fit-outs. Most businesses need equipment before it has had a chance to pay for itself, and paying cash can drain the working capital you need for wages, stock and growth.
Equipment finance spreads the cost over the working life of the asset. But chattel mortgages, finance leases, hire purchase and operating leases all treat ownership, GST and tax differently, and the cheapest monthly repayment is not always the best outcome for your business.
We compare asset finance options across our lender panel, including low doc options for self-employed borrowers and those with a newer ABN, and we coordinate with your accountant so the structure suits your tax position.
If you are also planning to buy or refinance a home, we look at both together. Business finance commitments can affect your home loan borrowing capacity, and it is far easier to plan for that upfront.
Types of Equipment Finance
Own it, lease it or rent it. The right choice depends on the asset and the business.
Each structure treats ownership, GST and tax deductions differently. Here is how the main options compare.
Chattel Mortgage
The most common option for businesses. You own the asset from day one and the lender takes security over it. Businesses registered for GST may be able to claim the GST on the purchase price upfront, and interest and depreciation may be deductible.
Finance Lease
The lender owns the asset and leases it to your business for an agreed term. Lease payments may be tax deductible, and at the end you can usually pay the residual to take ownership, refinance or upgrade.
Hire Purchase
The lender buys the asset and you hire it, with ownership passing to you once the final payment is made. It suits businesses that want to own the equipment eventually but spread the cost evenly.
Operating Lease and Rental
For equipment that dates quickly, like IT or medical technology, renting can make more sense than owning. Payments may be fully tax deductible and upgrading at the end of the term is straightforward.
What We Work Through With You
Finance that fits the asset, the business and the tax return.
Before we recommend any lender, we work through the details that decide whether the finance will actually help your business.
Tax and GST Treatment
Each structure affects your GST claims, deductions and balance sheet differently. We work alongside your accountant so the finance supports your tax position rather than complicating it.
Balloon or Residual Payment
A balloon lowers your regular repayments but leaves a lump sum due at the end. We size it to match the expected value of the asset and your cash flow, not just the lowest monthly figure.
New, Used or Private Sale
Lenders treat new, used and privately sold equipment differently, especially for older assets. We match you with lenders whose policy suits what you are buying and who you are buying it from.
Low Doc and New ABN Options
If your financials are not up to date or your ABN is relatively new, some lenders can still help based on alternative evidence such as BAS statements or bank statements. We know which ones.
Your Home Loan Plans
Equipment finance repayments can reduce how much you can borrow for a home. If a purchase or refinance is coming up, we plan the timing and structure of both so one does not block the other.
Supplier Invoice and Settlement
Lenders usually pay the supplier directly against a valid tax invoice. We coordinate with your supplier so the equipment is delivered and working as soon as possible.
How Equipment Finance Works
From supplier quote to equipment on site in five steps.
Here is what the equipment finance process typically looks like from start to finish.
Get a quote from your supplier
Find the equipment you need and get a quote or tax invoice. New, used, dealer or private sale can all be considered.
We assess the business and structure
We review your business, the asset and your goals, and recommend a structure, term and balloon that suit your cash flow and tax position.
Lender approval
We submit the application to the lender best suited to your situation and manage it through to approval.
Documents signed
You sign the finance documents, and we confirm the supplier invoice and any insurance the lender requires.
Supplier paid, equipment delivered
The lender pays the supplier directly and your equipment is released, so it can get to work straight away.
Working With Us
We move quickly because idle equipment costs money.
Equipment purchases are often tied to a job, a contract or a supplier deadline. We prioritise fast turnaround and clear communication throughout.
Free finance assessment
We review your business and the equipment you need, and confirm which structure and lenders make sense.
Lender comparison
We compare rates, fees, terms and balloon options across our asset finance panel.
Application submitted
We prepare and submit the application, and can submit the same day when your documents and supplier invoice are ready.
Settlement and beyond
We coordinate payment to the supplier and are here for your next asset, upgrade or home loan.
Example Scenario
How a new ABN holder can still get the gear.
Every business is different, but this illustrative example shows the kind of planning that goes into equipment finance. Names and figures are hypothetical.
A New Ute for a Growing Trade Business
A sole trader electrician has been running his own business for just over a year and needs a reliable ute to take on bigger jobs. His first tax return as a business owner is not lodged yet, so a standard application would struggle. We use his BAS statements and business bank statements to support a low doc chattel mortgage, set a modest balloon to keep repayments manageable, and talk to his accountant about the GST and depreciation. Because he and his partner plan to buy a home next year, we factor the new repayment into their borrowing capacity now.
The Team
You'll always know who's working on your file.
We keep our client load manageable by design. Every file is handled directly by Lorenzo or Tom, not passed to a junior processor or lost in a queue.
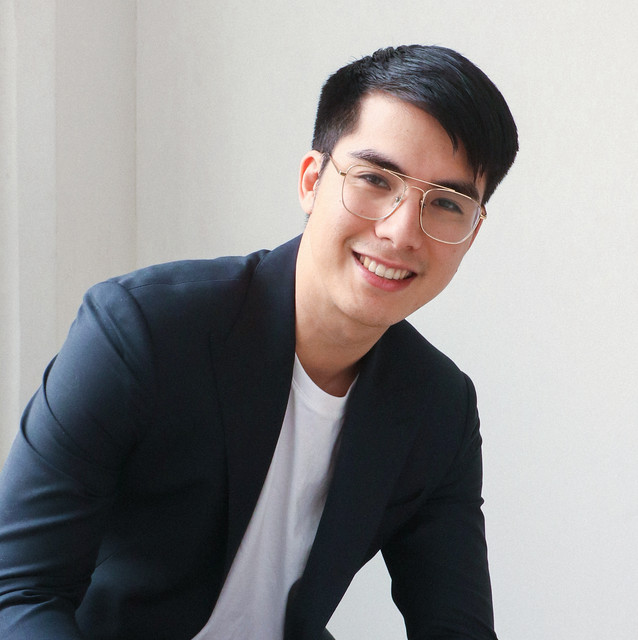
Lorenzo Suarez
Lorenzo runs the end-to-end process for most client files, from initial strategy and lender selection through to submission, approval, and settlement.
If your situation is straightforward, he will make it fast. If it is complex, he will find the way through.
Cert IV Finance & Mortgage Broking

Tom Williams
Tom co-founded Echidna Equity with a clear brief: personal service, genuine lender access, and a business that gives back. He oversees strategy and stays close to every client relationship.
When he says the job is not done until clients start defying gravity, he means it literally.
Cert IV Finance & Mortgage Broking
Why This Matters To Us Too
Good for business. Good for the bush.
Financing equipment is about growing your business, and it is worth knowing who you are working with. A portion of Echidna Equity's profit goes to the Australian Wildlife Conservancy, which protects native species and manages land across the country.
We do not think a finance broker can solve conservation on its own. But we can make sure some of what we earn, including from your business finance, goes toward looking after the country your business works in.
A share of our profits is donated to the Australian Wildlife Conservancy, supporting the protection of native species and habitat across Australia.
It's a small, ongoing commitment built into how we do business, the same one we made long before you found this page.
Common Questions
What people ask us about equipment finance.
Here are the questions business owners ask us most often about equipment and asset finance.
Get in Touch
Speak to a broker today.
Fill in the form and Lorenzo or Tom will be in touch within one business day. No obligation, no sales pitch, just a straight answer on what is possible for your business.
Book a free equipment finance assessment
We'll get back to you within one business day.
By submitting this form you consent to Echidna Equity contacting you regarding your enquiry. We do not share your details with third parties. General information only. This does not constitute financial or legal advice.
Message received.
Lorenzo or Tom will be in touch within one business day.
Get the equipment working for you sooner.
Book a free equipment finance assessment with Lorenzo or Tom. We will compare the options and tell you honestly which structure makes sense.
Echidna Equity Pty Ltd ACN 678 592 713. Credit Representative Number 562940 of Australian Credit Licence 384704. Suite 302, 13/15 Wentworth Ave, Sydney NSW 2000. Echidna Equity is based in Sydney and provides finance broking services to clients all over Australia. General information only. This does not constitute financial, tax or legal advice and does not take into account your objectives, financial situation or needs. Credit criteria, terms and conditions apply. Finance for business purposes may not be regulated under the National Consumer Credit Protection Act 2009. A broker fee may apply and will be disclosed in writing before you proceed. Tax and GST treatment depends on your circumstances; seek advice from your accountant. Interest rates, fees and product features are subject to change without notice.