
Building your next home?
Finance it stage by stage.
Echidna Equity structures construction loans so funds are released as your build progresses and you only pay interest on what has been drawn. No fees for our service.
Construction Finance in Sydney and All Over Australia
A construction loan works differently to a standard home loan.
With a standard home loan, the lender pays the full amount at settlement. With a construction loan, the money is released in stages as your builder completes each part of the job, from the slab through to handover. You typically pay interest only on the funds drawn so far, which keeps repayments lower while you may also be paying rent or an existing mortgage.
That structure adds moving parts. The lender needs your building contract, plans and council approvals, a valuation of what the finished home will be worth, and confidence that there is enough money in the loan to finish the job. If any of those pieces are out of line, the build can stall halfway through, which is exactly what we plan to avoid.
We compare construction products across 75+ lenders and match you with one whose policy suits your build type, your builder and your deposit, whether that is a house and land package, a knockdown rebuild or building on land you already own.
We are based in Sydney, but we arrange construction finance for clients building all over Australia. Most of the process happens by phone, video call and email.
Types of Construction Loans
Every build is different. The finance should be structured around yours.
The type of project you are taking on changes which lenders are a good fit and how the loan needs to be set up.
House and Land Package
You buy the land and sign a building contract at the same time. The loan typically funds the land at settlement, then releases construction funds in stages as the builder progresses. Some packages may also qualify for government first home buyer support.
Knockdown Rebuild
You already own the property and want to demolish and rebuild. We structure the existing mortgage and construction funds together and plan for where you will live, and what that costs, while the new home goes up.
Building on Land You Own
If the land is already paid off or has equity, that equity can often count toward your contribution. We work out how much the lender will recognise and how much cash you need to bring to the build.
Major Renovations and Extensions
Larger structural renovations, second storeys and granny flats are often funded as construction loans with progress payments, rather than a single lump sum top-up on your existing loan.
What We Work Through With You
A build that runs out of money halfway is the outcome we plan around.
Before we recommend any lender, we work through every variable that affects whether your construction loan will run smoothly from slab to handover.
Fixed-Price Building Contract
Most lenders want a fixed-price contract from a licensed builder. We review what is included and what is excluded, because items left out of the contract usually have to be funded by you, not the loan.
Valuation on an "As If Complete" Basis
The lender values the home as it will be when finished. If that valuation comes in below the land and build cost, you may need a larger contribution. We prepare for that before you sign anything.
Your Contribution Goes First
Lenders usually require your own funds to be used before they release theirs. We map out when your deposit, any grants and the loan funds are each drawn, so there are no surprise cash calls mid-build.
Variations and Contingency
Variations and cost overruns are common. We build a realistic buffer into the plan and explain how variations are handled by the lender if they come up during construction.
Interest-Only During the Build
Repayments are typically interest-only on the amount drawn while the home is being built, then convert to principal and interest once construction is complete. We model both phases so you know what to expect.
Builder Insurance and Approvals
Lenders typically require home warranty insurance, council or development approval and certified plans. We give you a checklist early so the paperwork does not hold up your first drawdown.
How a Construction Loan Works
From pre-approval to handover in five stages.
Here is what the construction loan process typically looks like from start to finish.
Budget and pre-approval
We confirm your borrowing power for the land and build combined, so you can choose a block, builder and design with a realistic budget in mind.
Contract, plans and valuation
Once you sign your building contract, we submit it with your plans and approvals. The lender orders a valuation of the finished home and issues formal approval.
Land settlement or first payment
If you are buying land, it settles first. If you already own it, the first progress payment is usually the builder deposit or the slab stage.
Progress payments during the build
As the builder completes each stage, such as frame, lock-up and fixing, they issue an invoice. You sign off, the lender may inspect, and funds are paid directly to the builder.
Completion and handover
After the final inspection and occupancy certificate, the last payment is released and your loan converts to standard principal and interest repayments.
Working With Us
We stay with you for the whole build, not just the approval.
Construction loans need more attention after approval than most home loans. We help you manage each drawdown request so the builder is paid on time and the project keeps moving.
Free construction assessment
We review your build plans, budget and contribution, and confirm whether your project is likely to be approved and by whom.
Lender selection
We compare construction policies across our panel and choose a lender whose rules suit your build type, builder and timeline.
Application and valuation
We prepare and submit the full application with your contract and plans, and manage the valuation and approval on your behalf.
Drawdowns and handover
We help coordinate each progress payment request through to completion, then review your loan once the build is finished.
Example Scenario
How a knockdown rebuild typically comes together.
Every build is different, but this illustrative example shows the kind of planning that goes into a smooth construction loan. Names and figures are hypothetical.
Rebuilding on the Family Block
A couple owns an older home with a modest mortgage and plenty of equity. They want to knock it down and build. We structure the existing debt and construction funds together, confirm the lender will value the finished home above the total cost, and plan their rent for the twelve months of the build into the budget. During construction they pay interest only on what has been drawn, and their loan converts to principal and interest once the occupancy certificate is issued.
The Team
You'll always know who's working on your file.
We keep our client load manageable by design. Every file is handled directly by Lorenzo or Tom, not passed to a junior processor or lost in a queue.
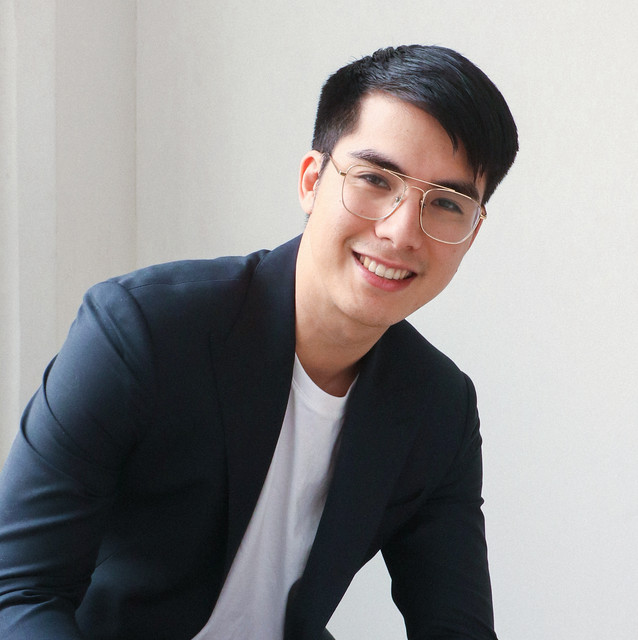
Lorenzo Suarez
Lorenzo runs the end-to-end process for most client files, from initial strategy and lender selection through to submission, approval, and settlement.
If your situation is straightforward, he will make it fast. If it is complex, he will find the way through.
Cert IV Finance & Mortgage Broking

Tom Williams
Tom co-founded Echidna Equity with a clear brief: personal service, genuine lender access, and a business that gives back. He oversees strategy and stays close to every client relationship.
When he says the job is not done until clients start defying gravity, he means it literally.
Cert IV Finance & Mortgage Broking
Why This Matters To Us Too
Building a home on Australian land. Giving some back to the wildlife that lives on it.
Building a new home is a big, exciting commitment, and it is worth knowing who you are working with. A portion of Echidna Equity's profit goes to the Australian Wildlife Conservancy, which protects native species and manages land across the country.
We do not think a mortgage broker can solve conservation on its own. But we can make sure some of what we earn from every settlement, including yours, goes toward looking after the country you are building on.
A share of our profits is donated to the Australian Wildlife Conservancy, supporting the protection of native species and habitat across Australia.
It's a small, ongoing commitment built into how we do business, the same one we made long before you found this page.
Common Questions
What people ask us about construction loans.
Construction finance has more steps than a standard home loan. Here are the questions we hear most often.
Get in Touch
Speak to a broker today.
Fill in the form and Lorenzo or Tom will be in touch within one business day. No obligation, no sales pitch, just a straight answer on what is possible for your build, wherever in Australia it is.
Book a free construction assessment
We'll get back to you within one business day.
By submitting this form you consent to Echidna Equity contacting you regarding your enquiry. We do not share your details with third parties. General information only. This does not constitute financial or legal advice.
Message received.
Lorenzo or Tom will be in touch within one business day.
Get the finance right before you sign with the builder.
Book a free construction assessment with Lorenzo or Tom. We will run the numbers, explain the options, and tell you honestly what your build will take.
Echidna Equity Pty Ltd ACN 678 592 713. Credit Representative Number 562940 of Australian Credit Licence 384704. Suite 302, 13/15 Wentworth Ave, Sydney NSW 2000. Echidna Equity is based in Sydney and provides finance broking services to clients all over Australia. General information only. This does not constitute financial, tax or legal advice and does not take into account your objectives, financial situation or needs. Credit criteria, terms and conditions apply. Construction loans are subject to lender approval of your building contract, plans and valuation. Costs not covered by your building contract may need to be funded by you. Interest rates, fees and product features are subject to change without notice.